Southwest Florida Real Estate: A Market Review Through September 2026
Naples, Fort Myers, Sanibel & Captiva, Fort Myers Beach and Beyond
Southwest Florida entered the fourth quarter with stronger sales activity than a year earlier, but meaningful differences in prices and inventory across communities.
In the Naples area, closed sales increased 15.1% during the first nine months of 2026, while the overall median closed price remained unchanged at $600,000. Third-quarter closings increased 7.1%.
These results show more properties changing hands, but they do not indicate uniform price appreciation. Single-family homes, condominiums and coastal properties continue to follow different paths. Understanding those differences is essential when evaluating a purchase or preparing a property for sale.
Naples | Sales increase across three reporting periods
The Naples Area Board of REALTORS® reports on Collier County excluding Marco Island. Its September statistics show:
- September: 623 closed sales, compared with 608 a year earlier—an increase of 2.5%.
- Third quarter: 1,995 closed sales, compared with 1,863—an increase of 7.1%.
- January through September: 7,246 closed sales, compared with 6,298—an increase of 15.1%.
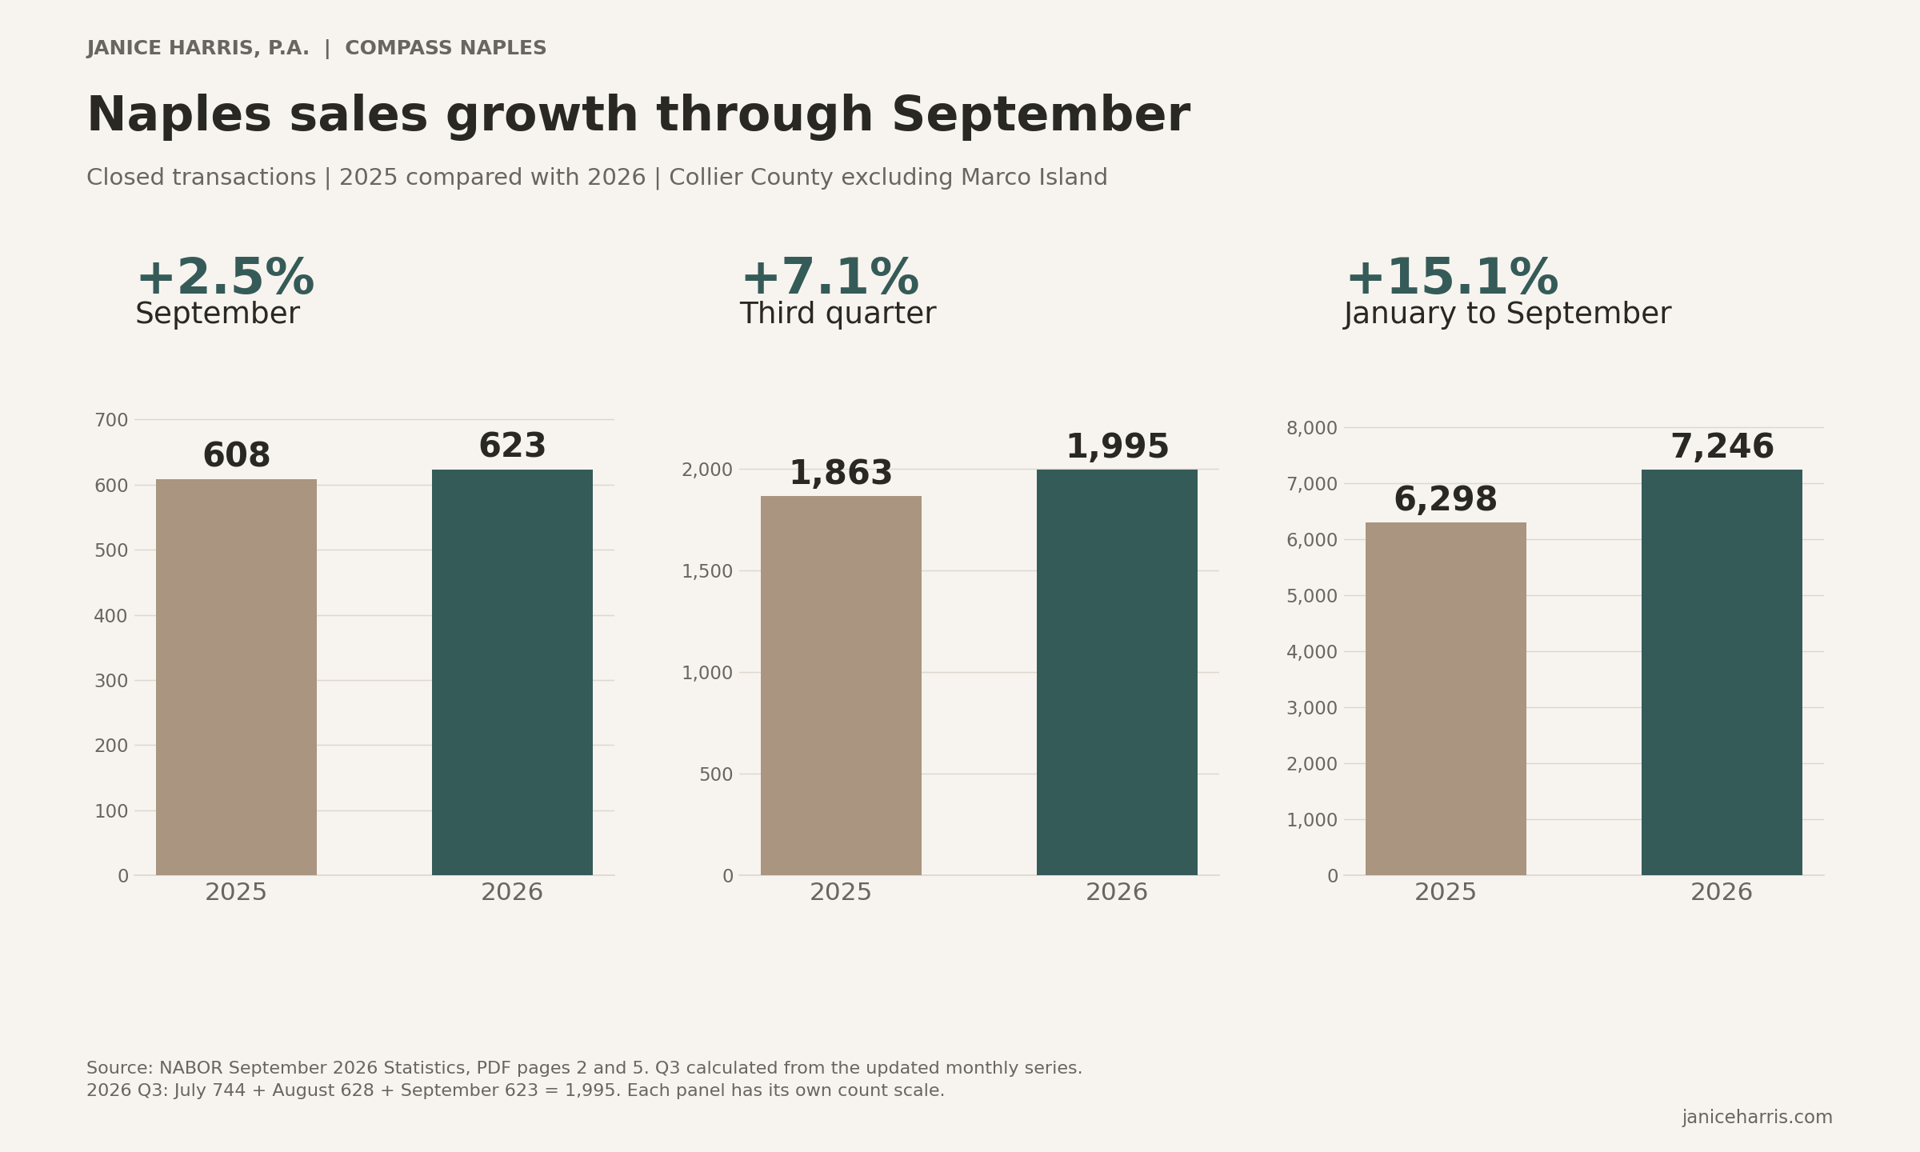
Source: NABOR September 2026 Statistics. Third-quarter totals use the revised monthly figures in that report.
The nine-month total also exceeded the same period in 2024 by 12.7%. However, the pace of year-over-year sales growth was slower in the third quarter than across the first nine months.
September pending sales offer another consideration. Signed contracts declined 6.8% to 702, even though year-to-date pending sales remained 19.0% above the prior year. Whether that monthly decline carries through to future closings will be worth watching.
Naples | Inventory tightens, while pricing varies
September’s overall median closed price increased 4.5% to $575,000, compared with $550,000 a year earlier. The January–September median remained unchanged at $600,000.
Active inventory declined 17.3% to 4,240 properties, and months of supply decreased from 7.8 to 5.5. Average days on market fell from 107 to 99, while sellers received an average 94.8% of current list price, compared with 93.9% a year earlier.
Buyers nevertheless gained fresh choices during September. Active inventory increased by 147 properties from August, and new listings rose from 792 to 1,073, approximately 35%.
Single-family homes and condominiums showed a clear pricing difference:
- Single-family homes: September median price of $747,500, up 3.1%. The January–September median was $760,000, up 3.5%.
- Condominiums: September median price of $400,000, down 2.4%. The January–September median was $438,000, down 2.7%.
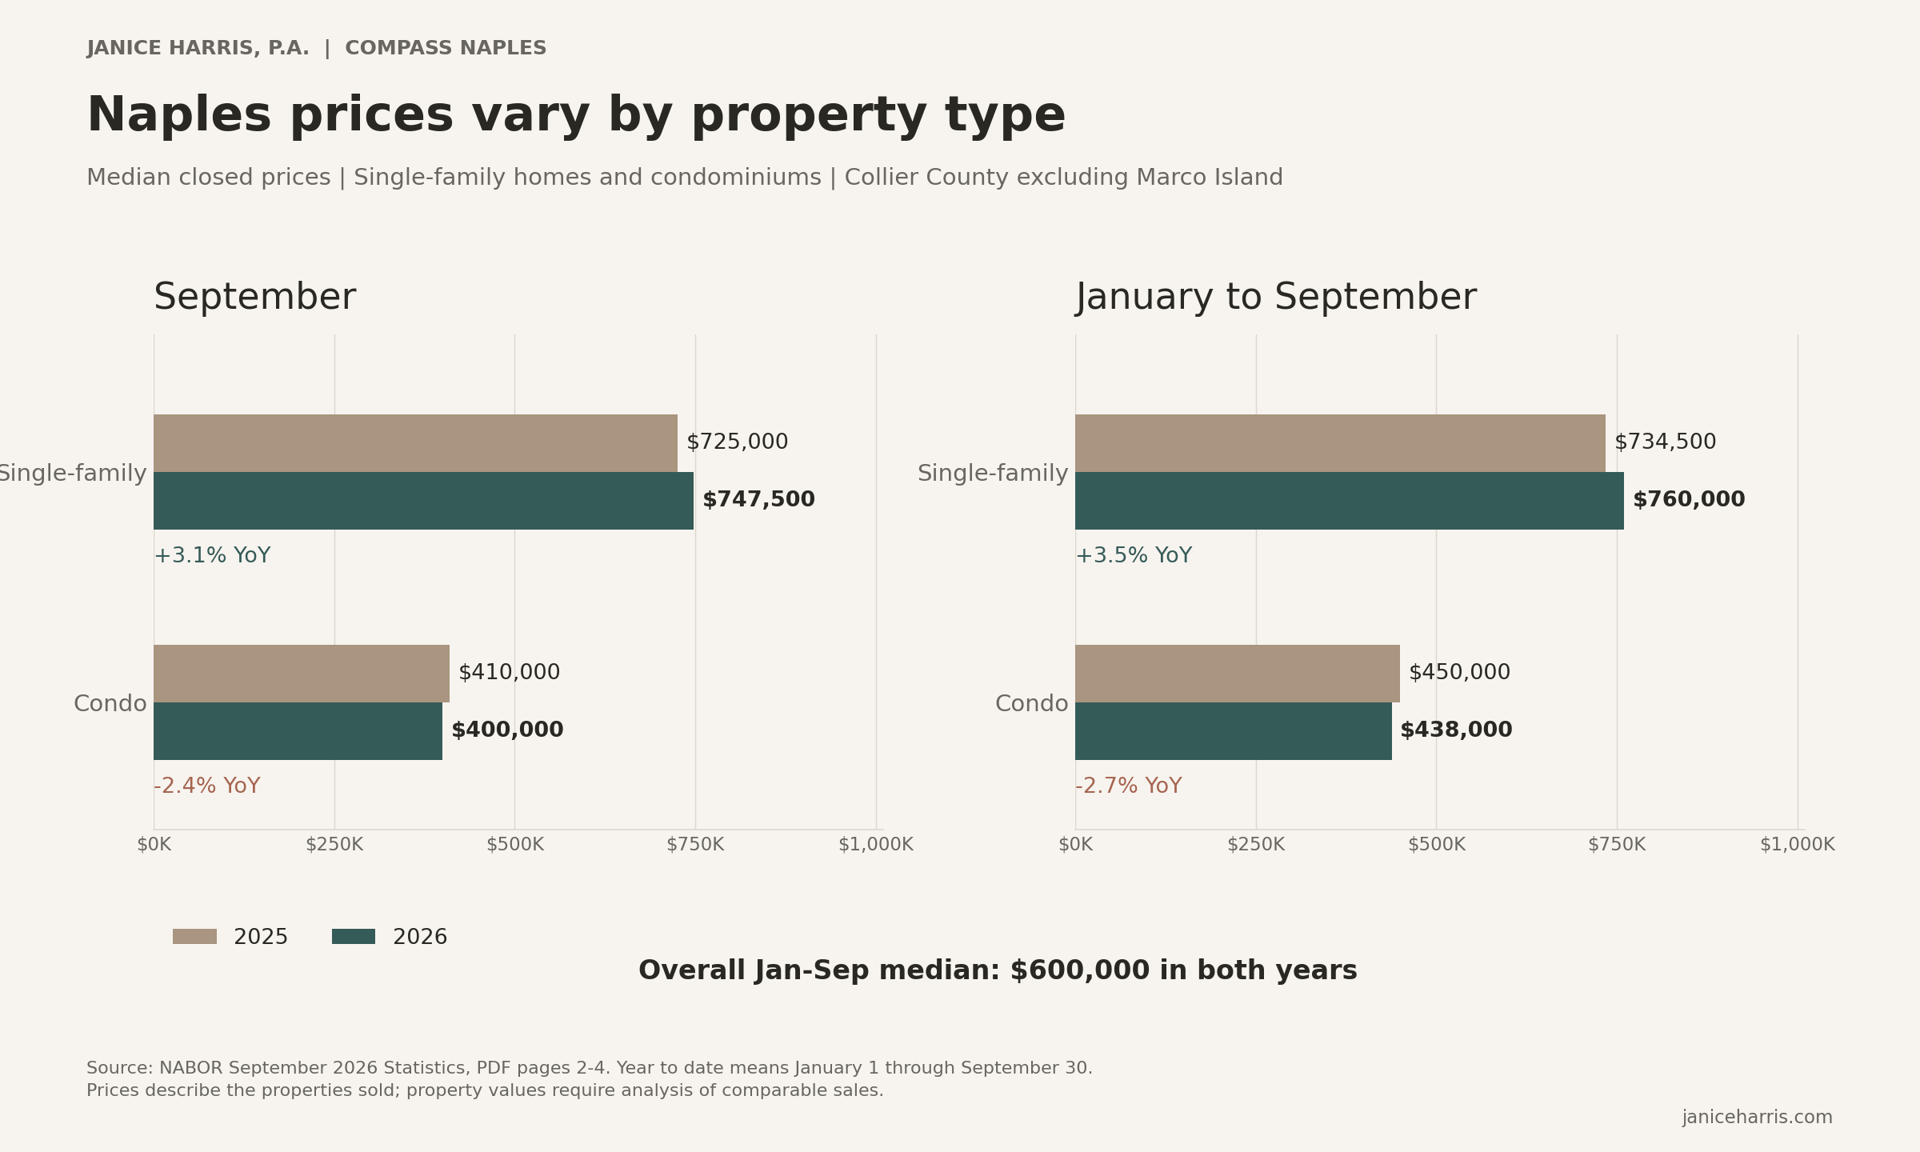
Source: NABOR September 2026 Statistics. Monthly and year-to-date comparisons are shown separately.
Condominium closings increased 20.1% year to date, compared with 10.5% for single-family homes. More condo transactions alongside a lower median price indicate improving sales activity with continued price sensitivity.
Median prices reflect the mix of properties sold. They should not be interpreted as the change in value of every home.
Coastal Naples | More transactions, selective pricing
NABOR’s Naples Beach area—ZIP codes 34102, 34103 and 34108—illustrates why transaction volume and pricing should be evaluated separately.
During January through September:
- Single-family closed sales increased 12.5%, from 417 to 469. The median closed price declined 3.3%, from $3 million to $2.9 million.
- Condominium closed sales increased 27.0%, from 685 to 870. The median closed price declined 7.3%, from $1,135,000 to $1,052,500.
Across the broader Naples market, the luxury brackets also recorded stronger transaction activity. On NABOR’s rolling 12-month comparison, sales between $1,500,001 and $5 million increased 33.6%, while sales above $5 million increased 20.3%. Median prices within those brackets declined 2.4% and 1.7%, respectively.
For a Park Shore condominium or an Olde Naples home, these figures provide context. Pricing still requires a closer look at the building or neighborhood, condition, competing listings and recent comparable sales.
Fort Myers | A different story for homes and condos
The Royal Palm Coast REALTOR® Association’s detailed Fort Myers Region tables show a pronounced difference between property types.
Single-family homes
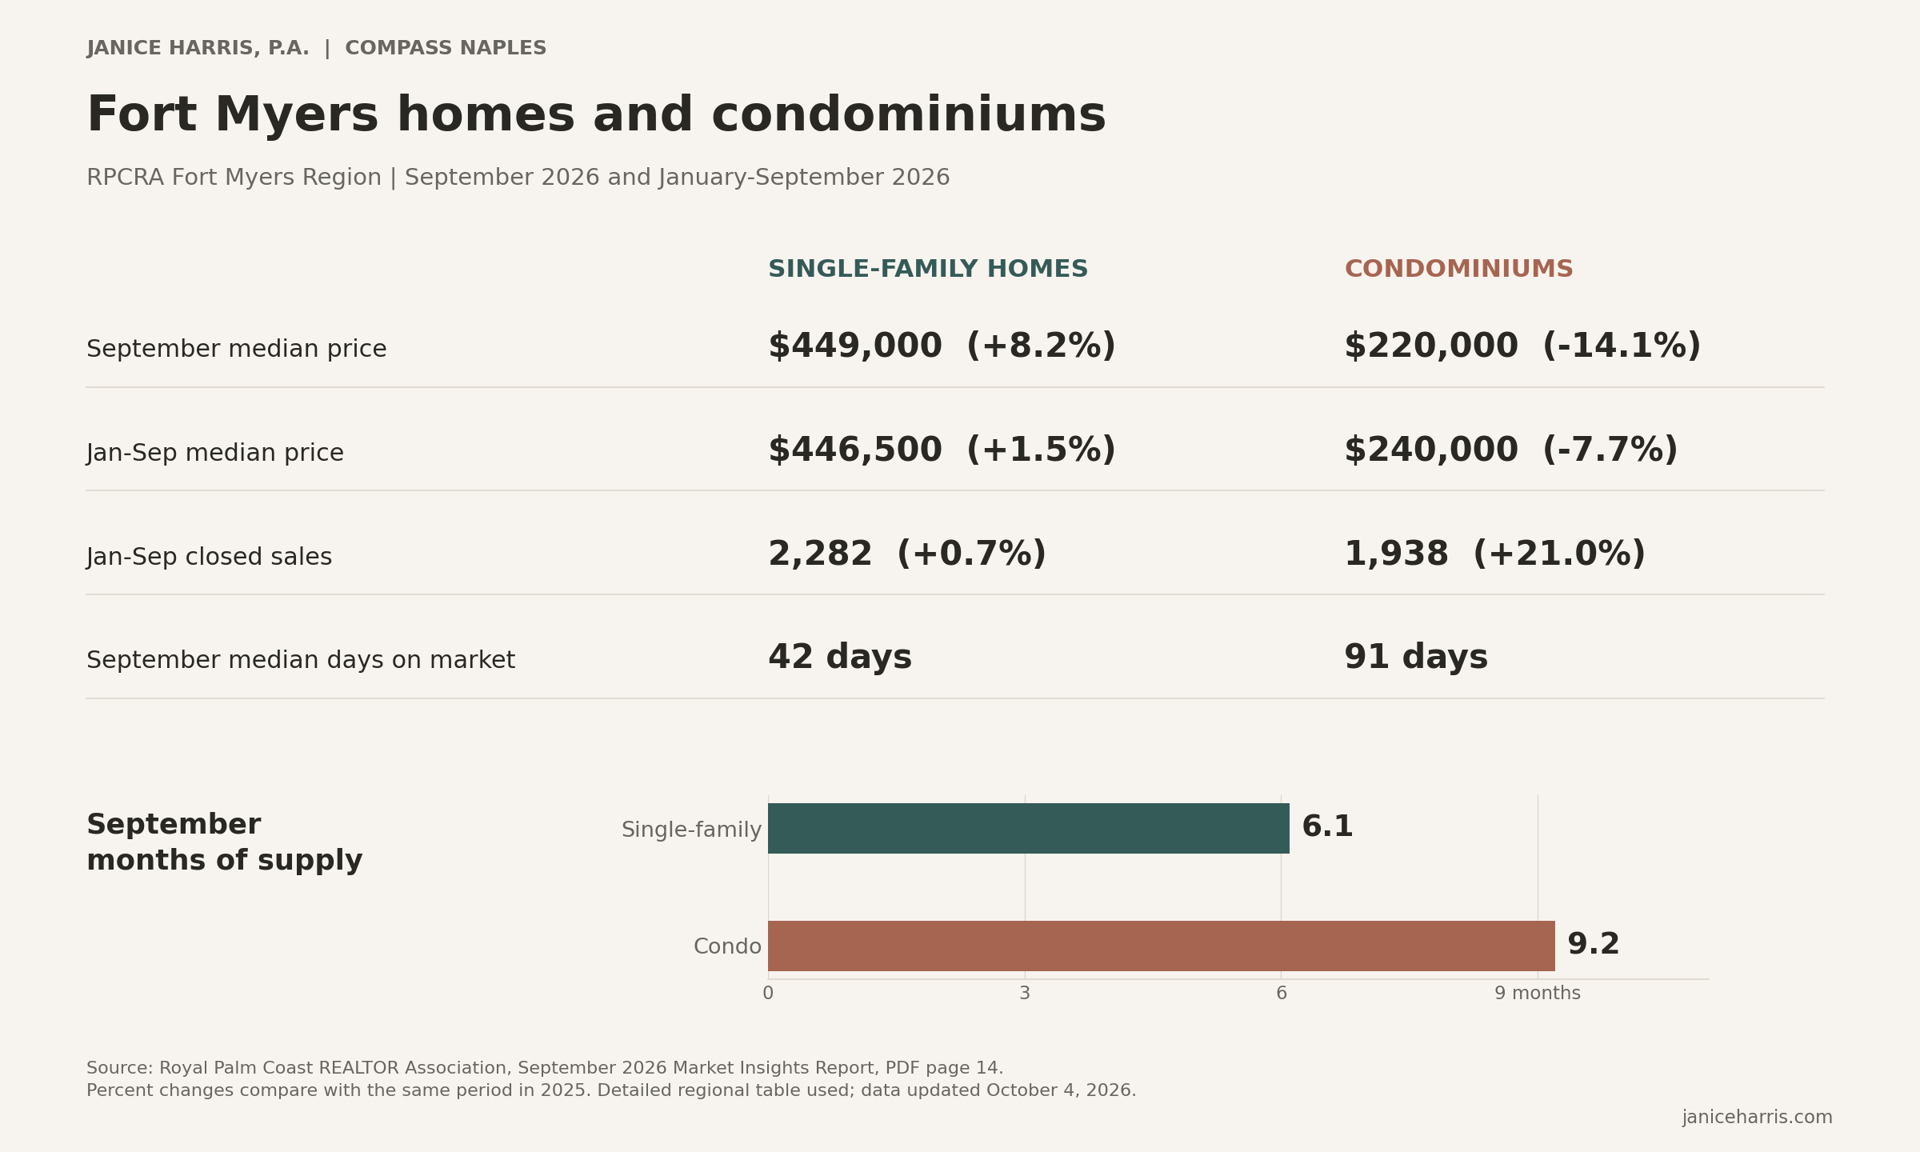
September recorded 208 closings, up 5.1%, and a median sold price of $449,000, up 8.2%. Inventory represented 6.1 months of supply, with median days on market of 42.
For January through September, closings increased 0.7% to 2,282, while the median price rose 1.5% to $446,500.
Condominiums
September recorded 157 closings, up 10.6%, but the median sold price declined 14.1% to $220,000. Supply stood at 9.2 months, with median days on market of 91.
For January through September, condo closings increased 21.0% to 1,938, while the median price declined 7.7% to $240,000.
Source: RPCRA September 2026 Market Insights Report, Fort Myers Region detailed tables.
Condo sales improved more rapidly, but greater supply, longer selling times and lower median prices suggest buyers remained selective.
For waterfront purchases, practical boating access, dock and lift condition, insurance and ongoing ownership costs deserve attention alongside the purchase price.
Sanibel & Captiva | Island sales rebound
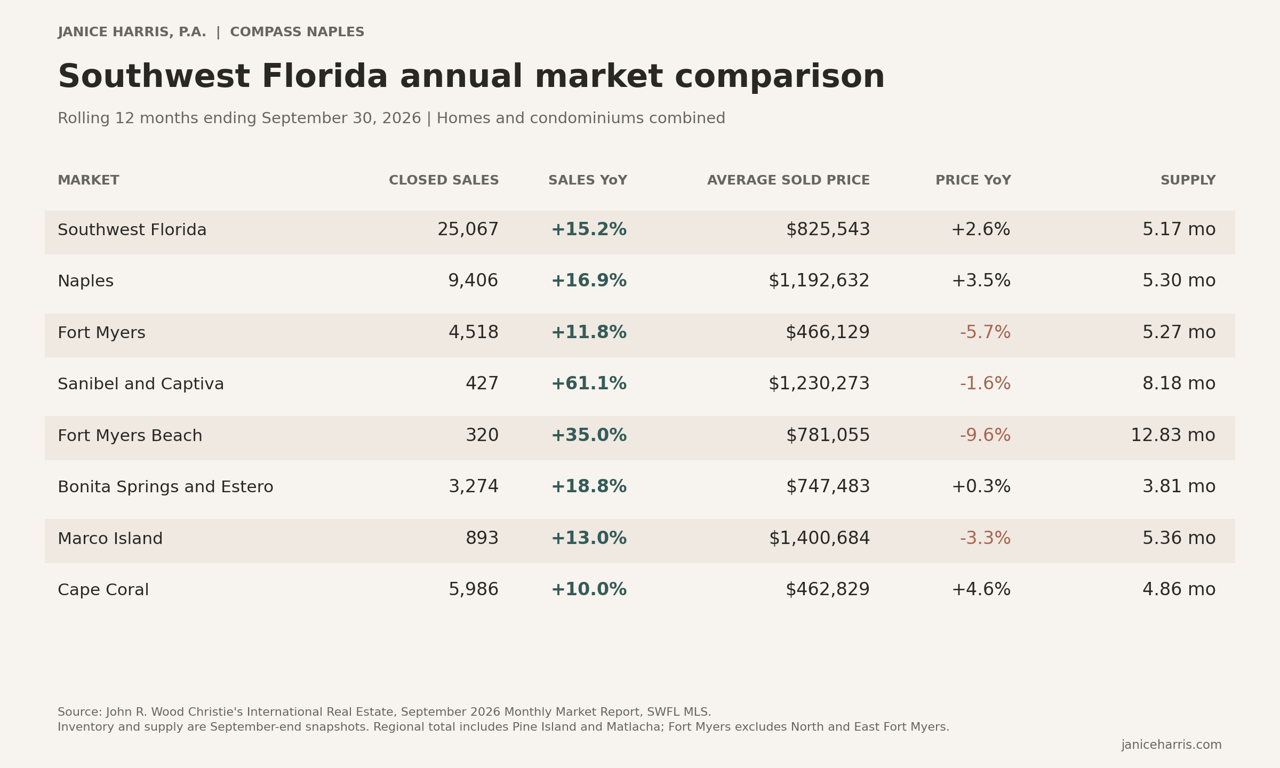
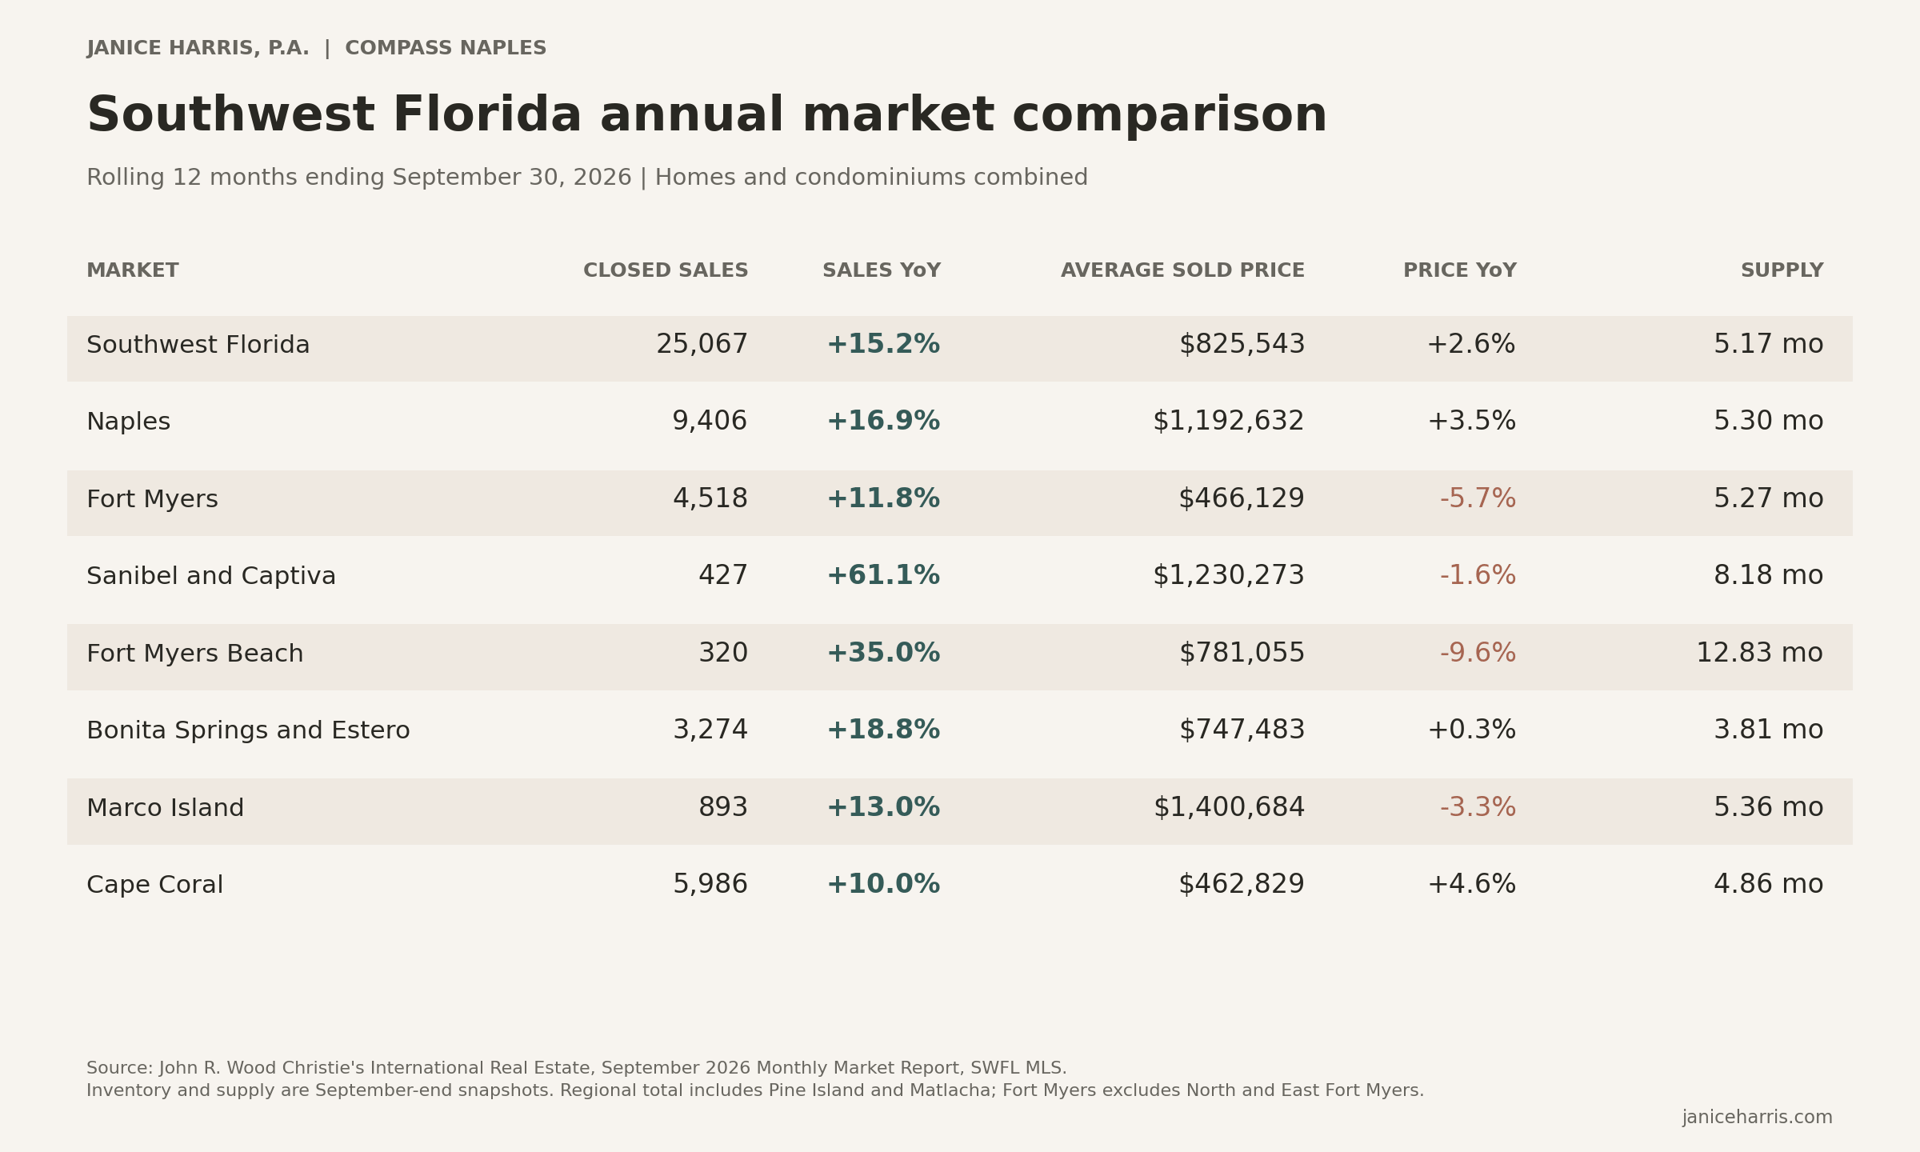
John R. Wood Christie’s International Real Estate reports 427 closings in Sanibel and Captiva during the 12 months ending September 30, 2026, an increase of 61.1% over the preceding 12 months.
The average sold price was $1,230,273, down 1.6%, while September-end supply stood at 8.18 months.
The substantial increase in transactions signals stronger sales activity, although average prices did not rise with volume. For island buyers, renovation history, building condition, insurance, association finances and remaining rebuilding obligations remain important parts of the analysis.
Fort Myers Beach | More activity, considerable choice
Fort Myers Beach recorded 320 closings over the same rolling annual period, an increase of 35.0%.
The average sold price declined 9.6% to $781,055, and supply stood at 12.83 months—substantially above Naples’ 5.30 months in the same publisher’s report.
This combination of rising sales and substantial available supply calls for careful property-level comparisons. Condition, location, renovation requirements and the mix of properties sold can all influence the reported average.
Other communities | Regional averages tell only part of the story
Using the same rolling 12-month period and source:
- Bonita Springs and Estero: 3,274 closings, up 18.8%; average sold price $747,483, up 0.3%; 3.81 months of supply.
- Marco Island: 893 closings, up 13.0%; average sold price $1,400,684, down 3.3%; 5.36 months of supply.
- Cape Coral: 5,986 closings, up 10.0%; average sold price $462,829, up 4.6%; 4.86 months of supply.
Source: John R. Wood September 2026 Monthly Market Report. Sales cover the rolling 12 months ending September 30; supply reflects the September-end snapshot.
These differences reinforce the importance of comparing communities individually. Similar growth in sales can occur alongside very different pricing and inventory conditions.
Hendry County | A separate local comparison
Hendry County, including LaBelle and Clewiston, offers alternatives for buyers seeking acreage and rural surroundings. Nearby Alva is in Lee County.
The RPCRA overview combines Lee and Hendry counties and excludes Bonita Springs and Estero. It should therefore not be used as a standalone Hendry County price benchmark.
For an acreage or rural property, a useful comparison should match the county, property type, parcel size and relevant property characteristics.
What does this mean for buyers and sellers?
For sellers, stronger transaction activity is encouraging, but pricing should reflect the specific competition. Lower overall inventory does not eliminate price sensitivity, particularly in condominium and coastal markets.
For buyers, available supply and ownership costs matter alongside the asking price. Association fees, reserves, insurance and property condition can materially change the economics of otherwise similar homes.
As winter approaches, I will be watching whether September’s softer Naples pending sales affect closings, how quickly new seasonal listings are absorbed, and whether condominium sales continue to improve as prices adjust.
Whether you are considering a Gulf-front condominium, a boating property, an island retreat or a home with acreage, I would be happy to review the figures for your community and put them in the context of your plans.
Janice Harris, P.A.
Real Estate Advisor | Compass Naples
janiceharris.com
Sources and reporting periods
Naples: NABOR September 2026 statistics and market report, covering Collier County excluding Marco Island. Third-quarter totals are calculated from the September report’s updated monthly series.
Fort Myers: Royal Palm Coast REALTOR® Association September 2026 Market Insights Report, using the detailed Fort Myers Region tables.
Regional comparisons: John R. Wood Christie’s International Real Estate September 2026 market report, using each market’s published geographic definition.
September figures cover that month. Year to date covers January–September; the third quarter covers July–September. Rolling annual figures cover October 1, 2025–September 30, 2026. These reporting periods are distinct. Average and median prices are different measures and can change with the mix of properties sold. Geographic definitions and supply calculations vary by publisher. Percentages are rounded.